DSCR WITHOUT THE BS. HERE’S HOW IT ACTUALLY WORKS.
Forget the complicated lender jargon. DSCR is really about understanding the relationship between a property’s qualifying rental income and the qualifying housing expense used to evaluate the deal.
WHAT THE HECK DOES DSCR EVEN MEAN?
DSCR stands for Debt Service Coverage Ratio. The name sounds complicated. The basic concept doesn’t have to be.
DSCR is a way of comparing qualifying rental income with the qualifying housing expense used by the applicable loan program.
A DSCR EXAMPLE YOU CAN ACTUALLY UNDERSTAND.
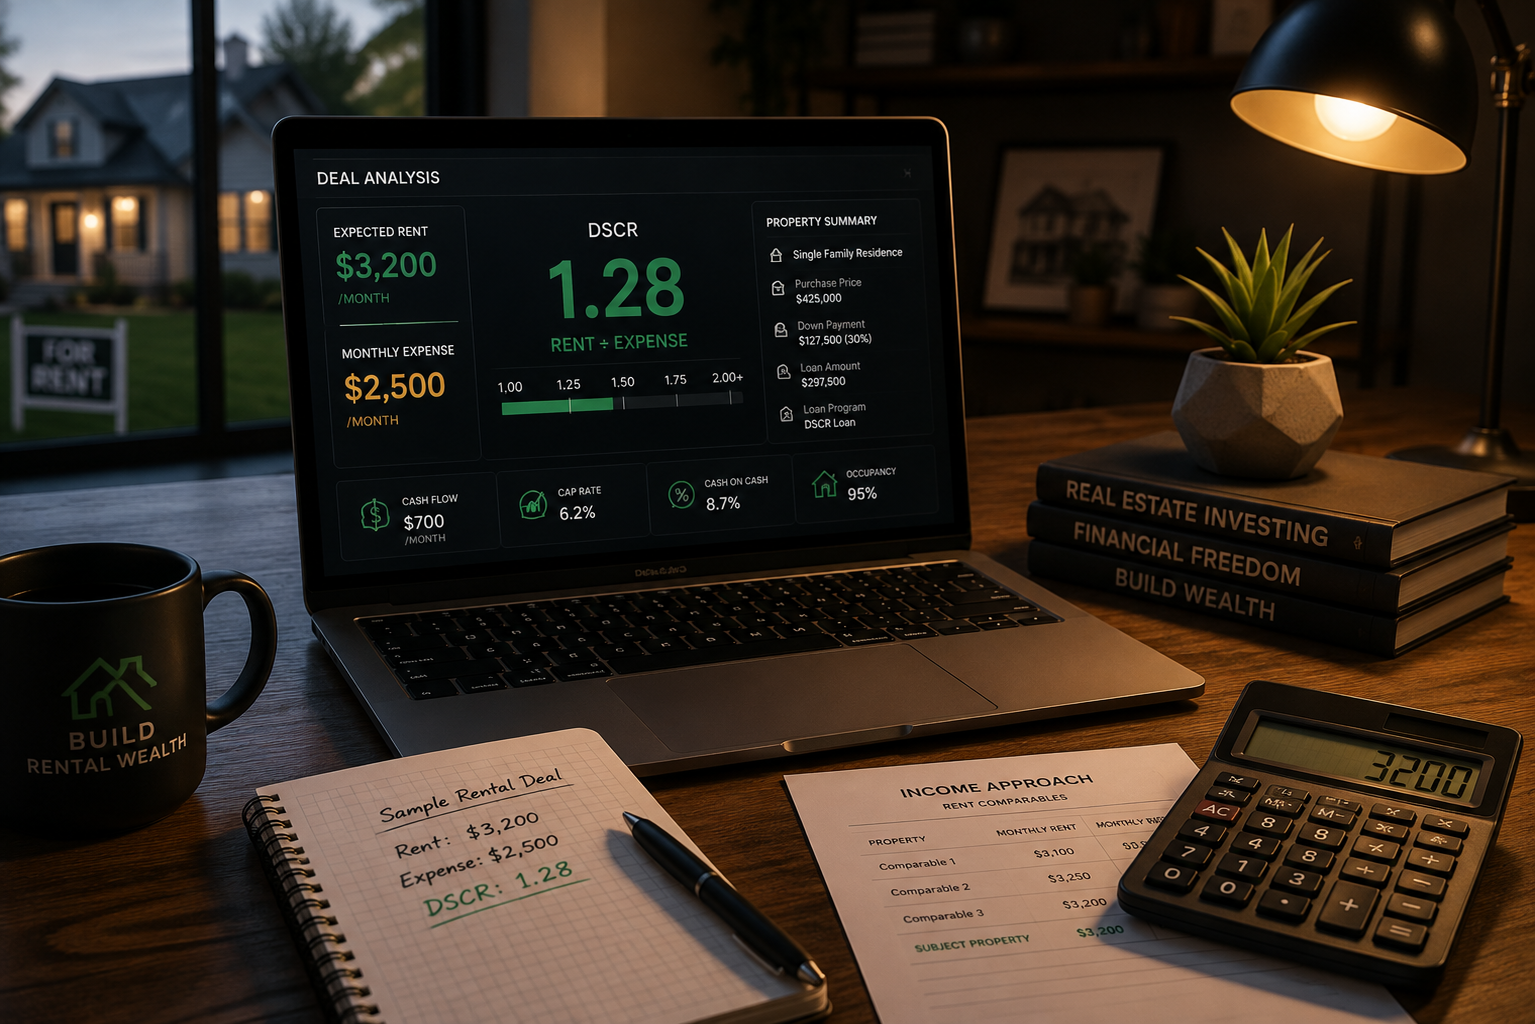
Imagine a rental property with qualifying monthly rent of $3,200 and a qualifying monthly housing expense of $2,500.
In this simplified example, qualifying rental income is 1.28 times the qualifying monthly housing expense.
SO WHAT COUNTS AS THE EXPENSE?
This is where people get into trouble when they assume every lender calculates DSCR exactly the same way.
The principal portion of the applicable mortgage payment.
The interest portion of the applicable mortgage payment.
Applicable real estate taxes associated with the property.
Applicable property insurance used in the housing expense.
Applicable HOA or association dues may be included.
Exact DSCR methodology varies by lender and loan program. The qualifying rent, expense calculation and required DSCR should always be confirmed for the specific financing scenario.
WHAT DOES THE NUMBER TELL YOU?
Think of the ratio as a quick way to understand the relationship between qualifying rent and qualifying housing expense.
In the simplified calculation, qualifying rental income is below the qualifying housing expense.
Qualifying rental income and qualifying housing expense are equal in the simplified calculation.
Qualifying rental income exceeds the qualifying housing expense in the simplified calculation.
Minimum DSCR requirements can vary by lender, program, leverage, credit profile, property type and other underwriting factors.
THE PROPERTY MATTERS. SO DOES THE REST OF THE DEAL.
A strong DSCR doesn’t automatically mean a loan is approved. Investment-property financing can involve several additional eligibility and underwriting factors.
The exact combination depends on the lender and program. That’s why the entire scenario needs to be reviewed — not just one ratio.
DSCR MYTHS THAT NEED TO DIE.
DSCR gets marketed so aggressively that the actual financing sometimes disappears underneath the hype.
“DSCR MEANS NO REQUIREMENTS.”
No. Programs can still have requirements involving credit, equity, reserves, property eligibility, documentation and other underwriting criteria.
“A GOOD DSCR MEANS AUTOMATIC APPROVAL.”
A ratio is one part of a financing scenario. Approval still depends on the complete applicable underwriting requirements.
“EVERY LENDER CALCULATES IT THE SAME WAY.”
Qualifying rents, expenses, minimum ratios and program requirements can vary between lenders and programs.
“DSCR IS ONLY FOR EXPERIENCED INVESTORS.”
Some programs may permit first-time investors, while others may have different requirements. Eligibility depends on the specific program and scenario.
LET’S RUN YOUR NUMBERS.
Plug in a property’s rental income and estimated housing expense to see the basic DSCR relationship for yourself.