FORGET RENTAL #10. LET’S GET #1.
Every portfolio starts with one property. Learn how to find the opportunity, understand the numbers, explore financing and take your first real step toward becoming a rental-property investor.
THE ROAD TO RENTAL #1.
You don’t need to master real estate investing before you begin. You need to understand the next decision.
FIND THE DEAL.
Look for a property with a price, location, condition and realistic rent worth investigating.
ANALYZE THE DEAL.
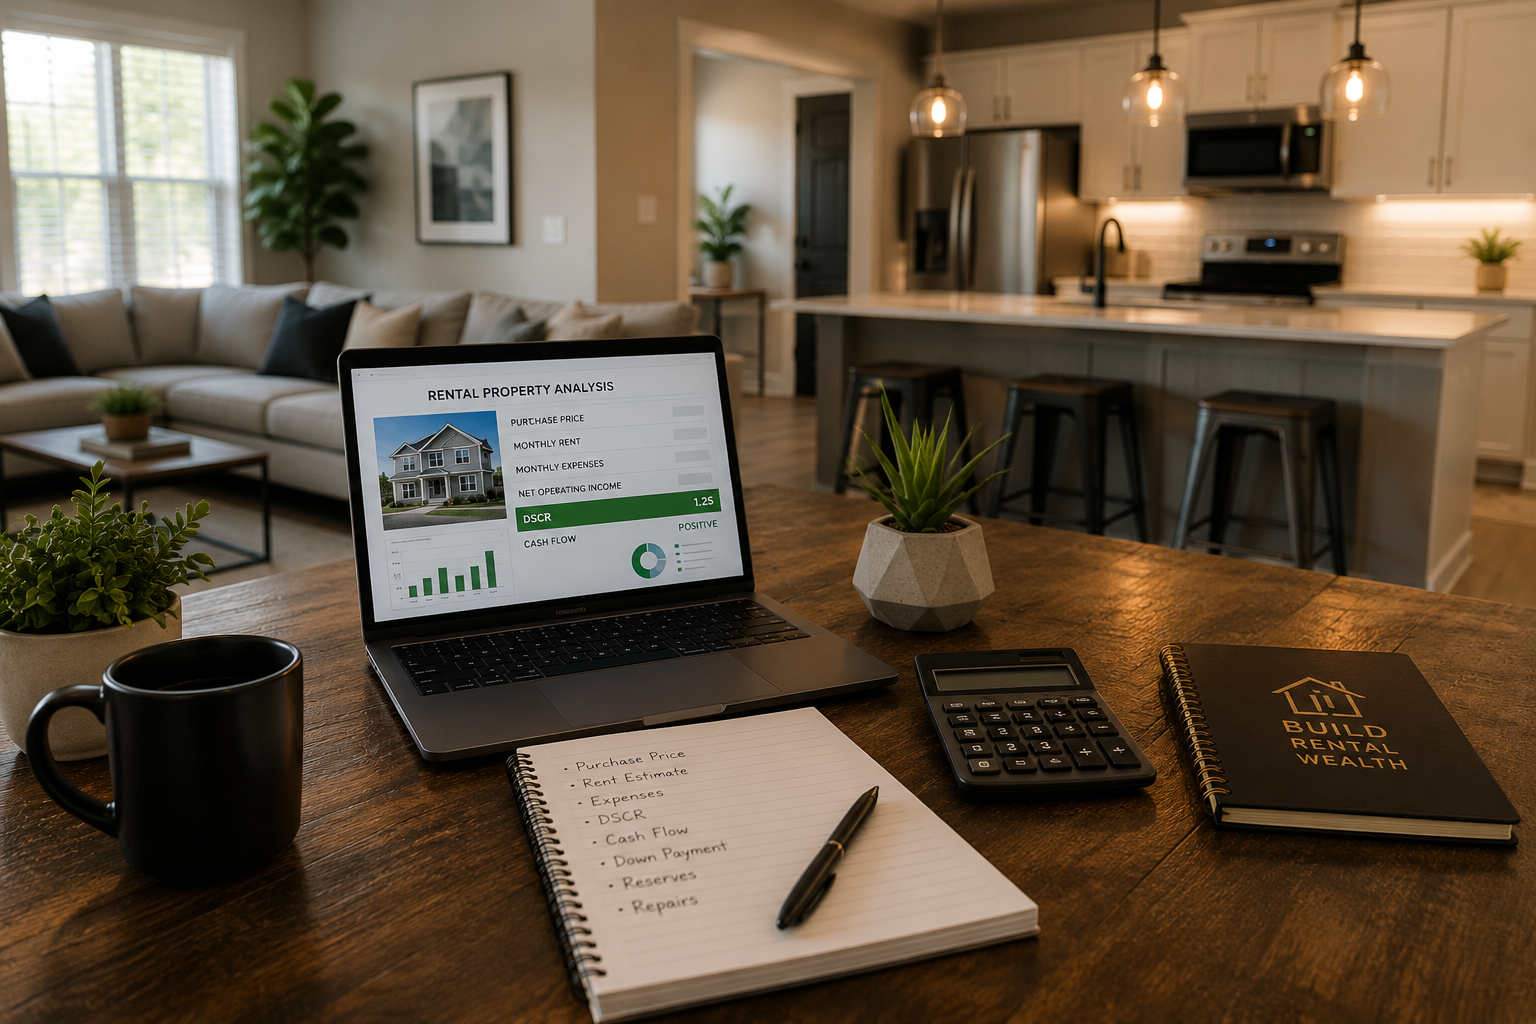
Estimate rent, housing expense and other property costs so you can understand what the numbers are telling you.
FIND THE FINANCING.
Review the property and borrower scenario to see which eligible investment-property programs may fit.
CLOSE. THEN BUILD.
Finish the transaction when requirements are satisfied and turn the experience from #1 into knowledge for #2.
WHAT SHOULD RENTAL #1 ACTUALLY LOOK LIKE?
Probably not the waterfront mansion from the homepage. Your first rental should begin with a property that makes sense for your budget, goals and financing.
FALL IN LOVE WITH THE NUMBERS.
A property can look amazing and still be a terrible investment. Before you start imagining tenants and cash flow, understand what the deal may actually look like.
HOW MUCH MONEY DO I ACTUALLY NEED?
There isn’t one universal number. The cash required can depend on the program, property, purchase price and your individual scenario.
DOWN PAYMENT
Investment-property financing generally requires meaningful equity, with exact requirements varying by program.
CLOSING COSTS
Title, appraisal, lender and transaction costs can add to the amount needed to complete the purchase.
RESERVES
Some programs may require additional liquid assets or reserves beyond the funds needed at closing.
PROPERTY NEEDS
Repairs, improvements, vacancies or preparation may affect how much cash you want available after closing.
ASK: “WHAT DO I NEED TO OWN THIS PROPERTY RESPONSIBLY?”
WHERE DOES DSCR FIT?
DSCR financing can allow eligible investment-property deals to be evaluated differently from a traditional owner-occupied mortgage.
The property’s rental income can become an important part of the analysis, along with credit, equity, reserves, property eligibility and lender requirements.
WHAT MAY A LENDER LOOK AT?
DSCR is important, but it isn’t the only part of an investment-property financing decision.
Type, condition, value and eligibility.
Expected or qualifying rental income.
Credit requirements vary by lender and program.
Down payment or equity can affect financing options.
Available funds may be part of program requirements.
Borrower/entity structure can matter depending on the program.
RENTAL #1. NOW YOU’RE BUILDING.
You found the property. You learned the numbers. You worked through the financing. And now the question changes.